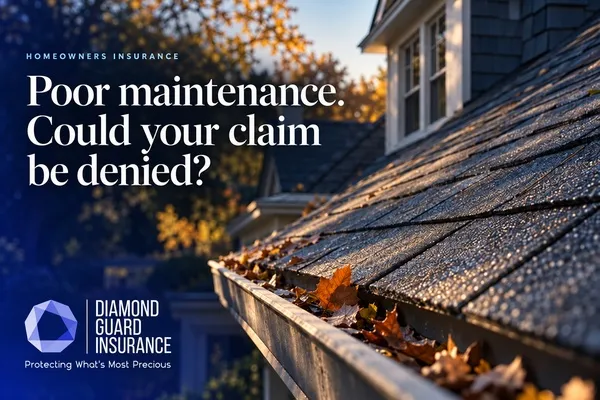
Can Homeowners Insurance Deny a Claim Because of Poor Maintenance?
What Texas Homeowners Need to Know
One of the biggest misconceptions about homeowners insurance is that if something damages your house, your insurance company will automatically pay to fix it.
Unfortunately, that's not always how it works.
Homeowners insurance is designed to cover certain types of losses. It's not intended to pay for routine maintenance, normal wear and tear, or every problem that develops over time.
But here's an important distinction: Poor maintenance doesn't automatically mean an insurance claim will be denied.
Let's look at three common situations.
1. The Dead Tree That Falls on Your House
Imagine you have a large tree in your backyard that's been dead for several years.
You know it needs to come down, but removing it could cost thousands of dollars.
So you decide to wait.
Then a storm comes through, the tree falls, and it damages your roof.
Will your homeowners insurance pay?
Possibly.
Many homeowners policies cover damage caused by falling trees. However, the insurance company may investigate the circumstances, including the condition of the tree and whether any policy exclusions apply.
The fact that a tree was dead doesn't automatically eliminate coverage. But knowingly leaving a dangerous tree standing creates an unnecessary risk.
The better approach: Have a hazardous tree evaluated by a qualified arborist and address the problem before it causes damage.
2. The Slow Plumbing Leak Nobody Fixed
Let's say you notice a small leak under your kitchen sink.
It's not much. Maybe a few drops every day.
You figure you'll get around to fixing it eventually.
Six months later, the cabinet is damaged, the flooring is warped, and there's mold behind the wall.
Will insurance cover it?
Maybe not.
Many homeowners policies exclude damage caused by continuous or repeated leakage over time.
Now compare that with a pipe that suddenly bursts and floods your kitchen.
That may be a covered loss, depending on your policy.
The difference often comes down to what caused the damage, how it occurred, and the specific coverage provisions.
The better approach: Repair leaks promptly and regularly inspect plumbing connections, appliances, and water heaters.
3. The Aging Roof
Texas weather can be tough on roofs.
Between hail, wind, heat, and years of exposure, roofs eventually wear out.
Suppose your roof is 20 years old and the shingles are deteriorating.
Can you file an insurance claim to replace it?
Generally, no. Insurance isn't designed to replace a roof simply because it's reached the end of its useful life.
But what happens if a hailstorm damages that same roof?
You may have coverage for the hail damage.
The insurance company will evaluate the cause and extent of damage, along with your policy's exclusions, deductibles, and roof settlement provisions.
An older roof may also be insured on an actual cash value basis, meaning depreciation could reduce the payment.
The better approach: Know the age and condition of your roof, maintain it appropriately, and understand how your insurance policy covers roof damage.
Why Maintenance Matters
Regular home maintenance does more than keep your property looking good.
It can help you:
Prevent avoidable damage.
Extend the life of expensive home systems.
Identify problems before they become emergencies.
Reduce the likelihood of insurance claims.
Maintain records that may help establish what happened if a loss occurs.
Simple tasks like checking for leaks, cleaning gutters, inspecting your roof, and removing hazardous trees can make a meaningful difference.
Does Every Maintenance Problem Result in a Denied Claim?
No.
This is where homeowners need to be careful about making assumptions.
An insurance company must evaluate the actual cause of the damage and apply the language of the policy.
For example, a roof may be old but still sustain covered storm damage. A plumbing system may need maintenance but also experience a sudden covered failure.
The existence of a maintenance issue does not necessarily mean every resulting loss is excluded.
Final Thoughts
Your homeowners insurance policy is an important financial safety net, but it shouldn't be your home maintenance plan.
The smartest approach is to maintain your property, address problems when you discover them, and understand what your policy does and doesn't cover.
At Diamond Guard Insurance, we believe helping homeowners understand these differences is part of helping them protect what matters.
Remember: The best insurance claim is often the one you never have to file.
Coverage varies by insurer, policy form, endorsements, exclusions, and circumstances of loss. Always review your specific policy.